What Is Net Debt? How It Measures a Company’s Financial Health and Debt Risk


Hello, this is MasterMind.
How can a company report billions of dollars in revenue and strong earnings growth, yet suddenly find itself under financial stress when the economy slows?
And why can another company carry billions of dollars of debt while continuing to invest aggressively during a market downturn?
The answer often lies beyond the headline debt number.
For investors analyzing U.S. companies, one of the most useful questions is not simply
“How much debt does this company have?”
A better question is
“After accounting for its cash, how much debt does the company really have to carry?”
That is what Net Debt helps us understand.
Net debt provides a clearer picture of a company's financial leverage, balance-sheet flexibility, refinancing risk, and ability to survive difficult economic environments.
For long-term investors, it can also reveal something even more important: which companies may still have strategic options when capital becomes expensive.
The Bottom Line
Net Debt is generally calculated by subtracting cash and cash equivalents from a company's interest-bearing debt. It helps investors estimate the company's effective debt burden and evaluate its financial resilience.
What Is Net Debt?
Net Debt measures how much financial debt would remain after accounting for a company's available cash and cash equivalents.
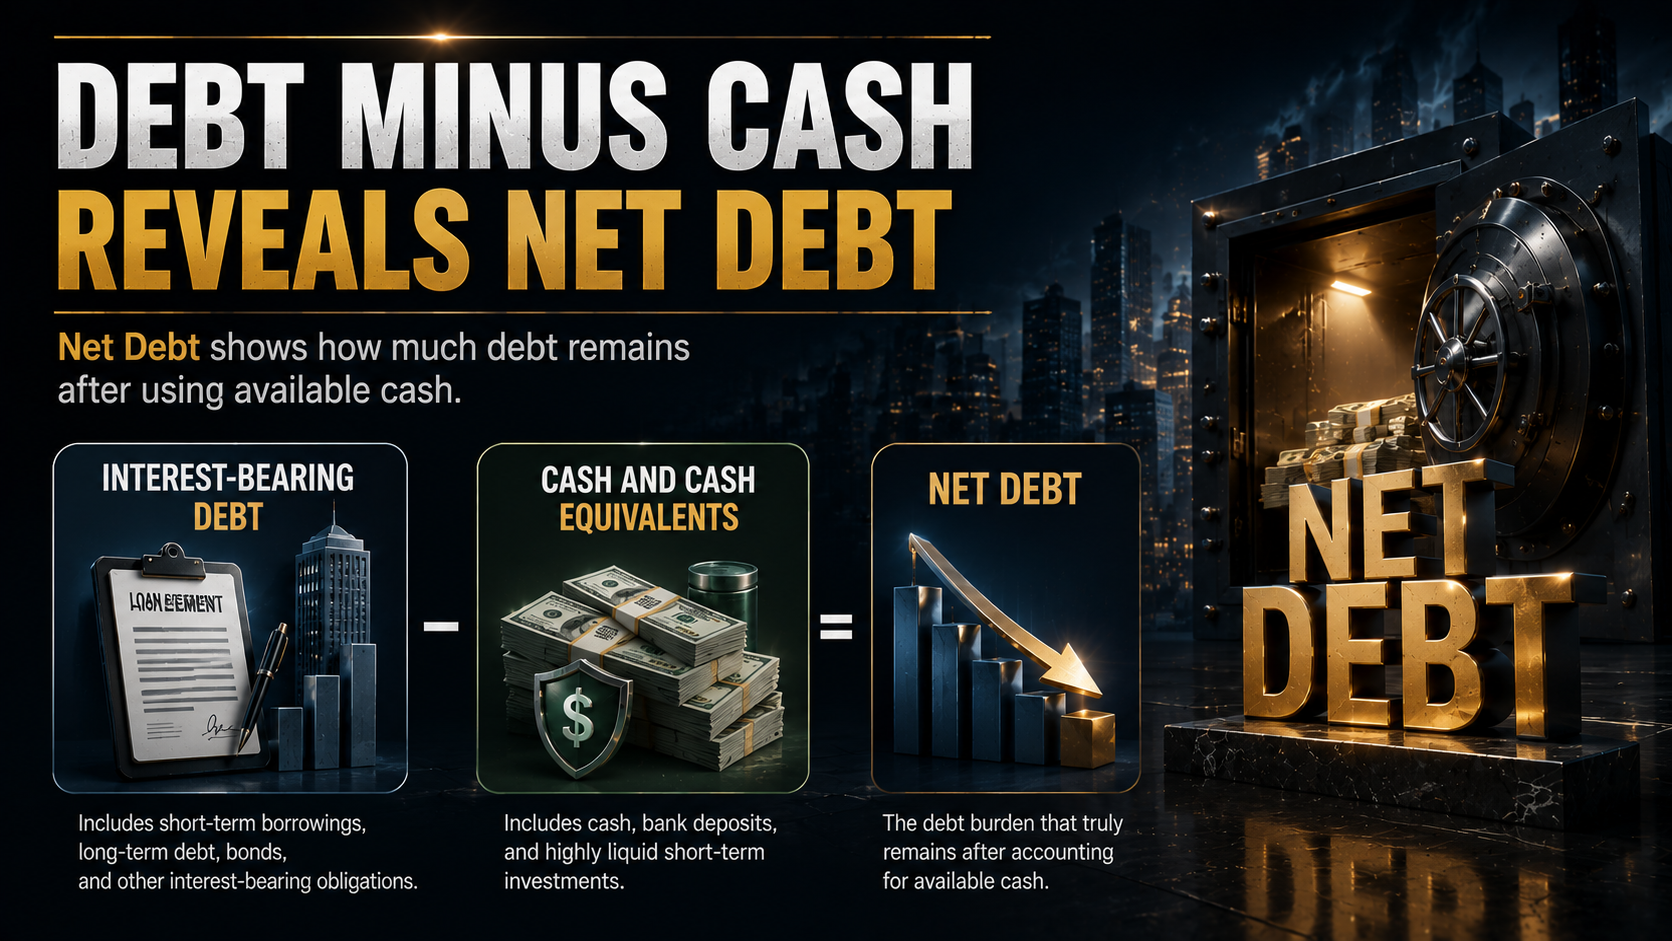
The basic formula is
Net Debt = Interest-Bearing Debt − Cash and Cash Equivalents
Depending on the financial database or analytical methodology being used, the exact definition can vary.
Interest-bearing debt commonly includes items such as
- Short-term borrowings
- Long-term borrowings
- Corporate bonds
- Other interest-bearing financial obligations
Cash and cash equivalents generally include
- Cash
- Bank deposits
- Highly liquid short-term investments that qualify as cash equivalents
Some analysts may also include certain short-term investments or lease obligations in their calculations.
This means investors should use a consistent definition when comparing companies.
The concept itself, however, is straightforward.
Imagine a company has
- $10 billion in interest-bearing debt
- $7 billion in cash and cash equivalents
Its net debt would be approximately
$10 billion − $7 billion = $3 billion
The company technically owes $10 billion, but its effective debt position looks very different once its liquidity is considered.
That distinction matters.
What Is Net Cash?
Sometimes a company's cash exceeds its financial debt.
Consider a business with
- $5 billion in debt
- $8 billion in cash
Its net debt would be
$5 billion − $8 billion = −$3 billion
Rather than describing this company as having negative net debt, investors commonly say it has approximately $3 billion of net cash.
A net cash position can provide significant financial flexibility.
The company may be able to fund capital expenditures, research and development, acquisitions, or shareholder returns without relying heavily on outside financing.
But net cash does not automatically make a company a good investment.
A company holding enormous amounts of cash while its core business deteriorates may still destroy shareholder value.
The more important question is
What return is management generating from the capital it controls?
Cash provides optionality. Capital allocation determines whether that optionality creates value.
How Net Debt Works
Net debt becomes especially useful when comparing companies that appear similar on the surface.
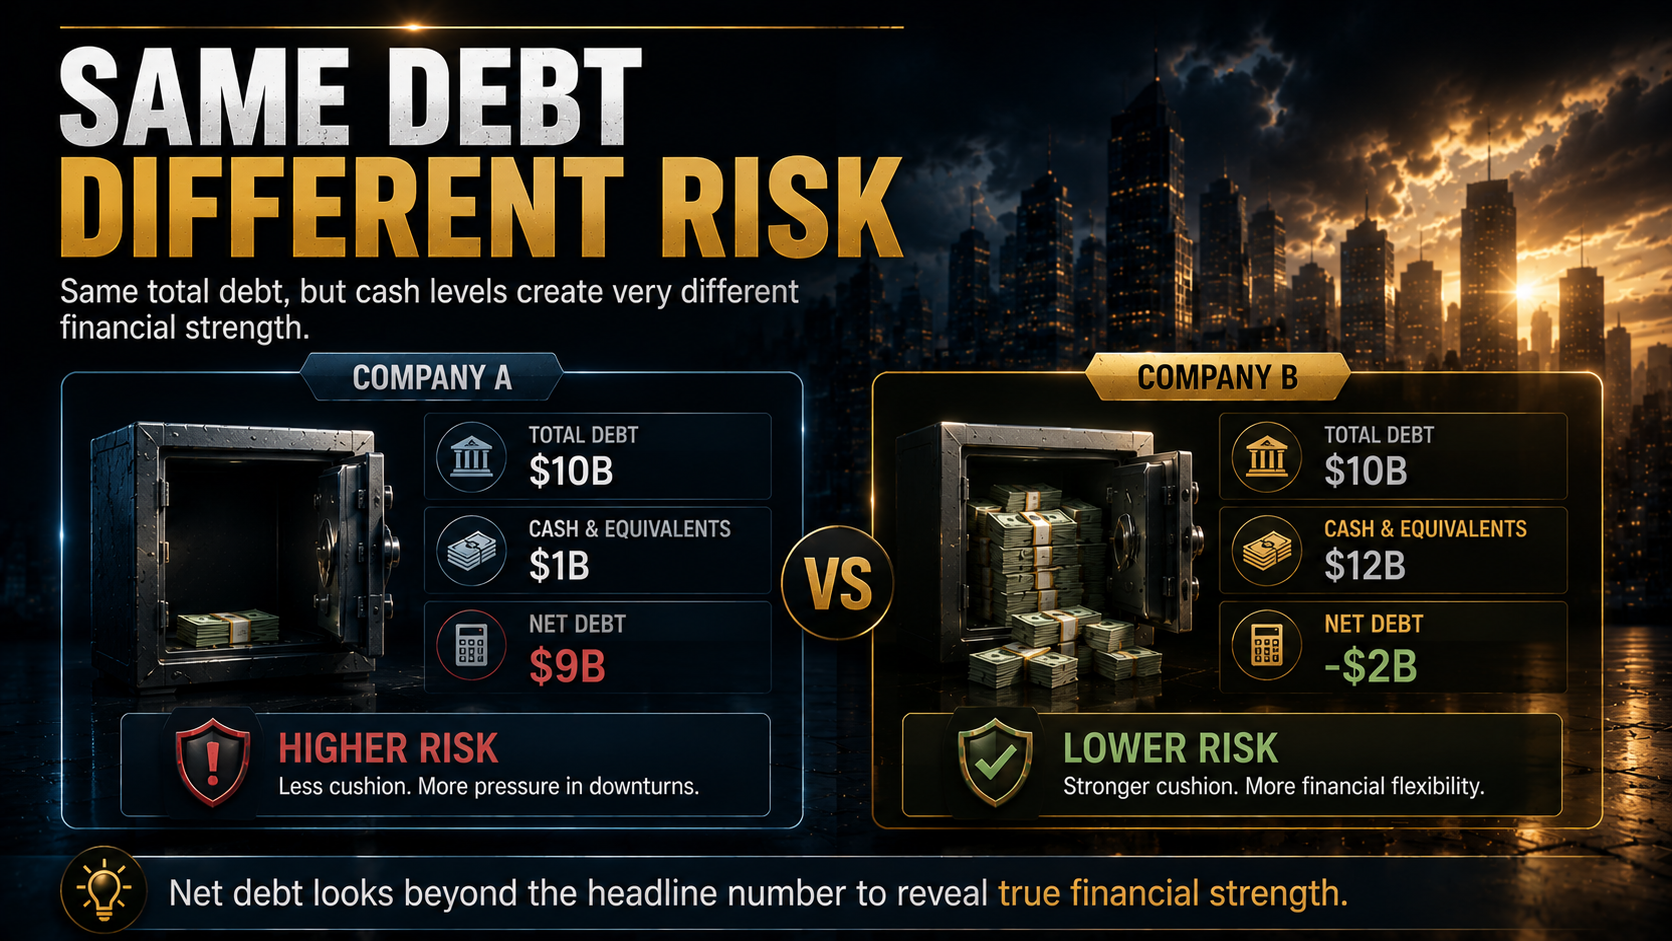
Suppose Company A and Company B both carry $10 billion of debt.
Company A holds $1 billion in cash.
Company B holds $12 billion.
| Metric | Company A | Company B |
| Interest-Bearing Debt | $10B | $10B |
| Cash | $1B | $12B |
| Net Debt | $9B | -$2B |
| Position | Net Debt | Net Cash |
Looking only at total debt would make the companies appear equally leveraged.
They clearly are not.
Company A has substantially less liquidity available relative to its debt burden.
Company B could theoretically repay all of its financial debt using existing cash and still retain approximately $2 billion.
This does not mean Company B is automatically the better investment, but its balance sheet provides greater financial flexibility.
That flexibility becomes particularly valuable when economic conditions deteriorate.
Why Is Net Debt Important?
Net debt matters because debt becomes more dangerous when money becomes expensive.
During periods of low interest rates and abundant liquidity, highly leveraged companies can often refinance existing debt relatively easily.
When financial conditions tighten, the equation changes.
The basic mechanism can look like this
Higher Interest Rates → Higher Financing Costs → Greater Interest Expense → Lower Cash Flow → Less Financial Flexibility
If an economic slowdown occurs at the same time, the pressure can become even greater.
Revenue may decline.
Margins may compress.
Cash generation may weaken.
But interest payments do not disappear simply because the economy has entered a recession.
Companies facing major debt maturities may also need to refinance at significantly higher interest rates.
This creates refinancing risk.
Companies with low net debt or substantial net cash may be less dependent on external capital markets and therefore better positioned to withstand periods of financial stress.
This leads to an important principle
In strong markets, investors often focus on growth. In difficult markets, they rediscover the value of liquidity.
Net Debt and Interest Rates
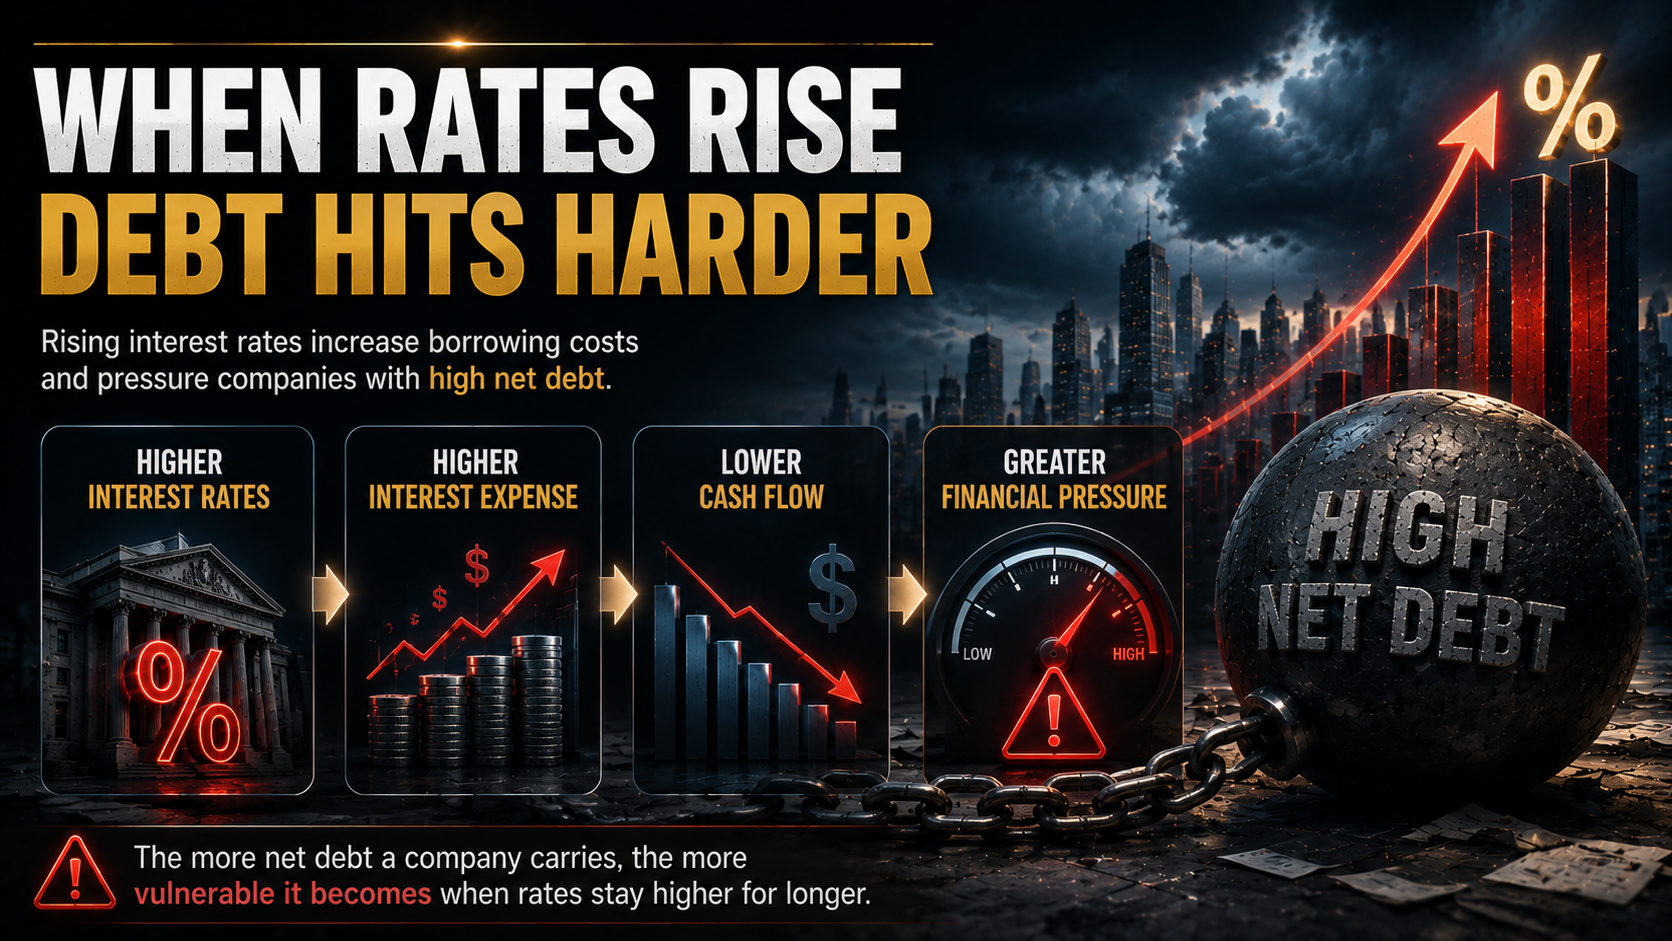
Interest rates are one of the most important macroeconomic variables affecting highly leveraged companies.
Suppose a business carries significant floating-rate debt.
When benchmark rates rise, its interest expense can increase relatively quickly.
Even companies with fixed-rate debt are not completely protected.
Eventually, bonds mature and loans need to be refinanced.
A company that borrowed at 3% may discover that refinancing the same debt now costs 6%.
The underlying business does not need to deteriorate for free cash flow to decline.
The cost of capital alone can change the economics.
This is why investors should examine not only net debt but also
- Debt maturity schedules
- Fixed-rate versus floating-rate debt
- Average interest rates
- Credit ratings
- Interest expense
- Access to capital markets
The amount of debt matters.
The price and maturity of that debt matter too.
Net Debt to EBITDA: A Key Leverage Ratio
Net debt becomes more meaningful when compared with a company's earnings capacity.
One of the most widely used leverage metrics is
Net Debt to EBITDA = Net Debt ÷ EBITDA
EBITDA stands for earnings before interest, taxes, depreciation, and amortization.
The ratio provides a rough indication of how large a company's net debt is relative to its operating earnings capacity.
Suppose a company has
- $10 billion of net debt
- $5 billion of EBITDA
Its Net Debt to EBITDA ratio would be
2.0x
Now imagine another company also carries $10 billion of net debt but generates only $2 billion of EBITDA.
Its ratio would be
5.0x
The absolute amount of net debt is identical.
The financial burden is not.
What Is a Good Net Debt to EBITDA Ratio?
There is no universal number that works across every industry.
Ratios around 2x to 3x may often be viewed as manageable in many businesses, while leverage above 4x or 5x can warrant closer scrutiny.
But these numbers should never be treated as rigid rules.
Utilities, telecom companies, infrastructure businesses, real estate-related businesses, and other companies with relatively predictable cash flows may operate with higher leverage.
Cyclical businesses may need much more conservative balance sheets because their earnings can fall rapidly during recessions.
The better approach is to compare
Company vs. Peers + Current Ratio vs. Historical Ratio + Debt vs. Cash Flow Stability
Context matters more than a single threshold.
Net Debt and Free Cash Flow
Another critical mistake is analyzing net debt without examining cash flow.
Debt is ultimately repaid with cash, not accounting earnings.
This makes Operating Cash Flow and Free Cash Flow essential companions to net debt analysis.
Imagine a company whose revenue is growing 20% annually.
That sounds impressive.
But suppose its net debt is also increasing every year.
Investors should ask
Is the business funding growth internally, or is it borrowing continuously to maintain that growth?
Now consider the opposite situation.
A company is producing consistent free cash flow while steadily reducing net debt.
That may indicate improving balance-sheet strength.
A useful analytical chain is
Net Debt → EBITDA → Operating Cash Flow → Free Cash Flow → Interest Expense → Debt Maturities
This transforms net debt from an isolated accounting number into a picture of the company's financial system.
How Net Debt Can Affect Stocks
Net debt can influence equity performance because debt holders have a claim on the business before common shareholders.
When leverage rises, a greater portion of the company's cash flow may be committed to interest and principal payments.
That leaves less capital available for
- Capital expenditures
- Research and development
- Acquisitions
- Dividends
- Share repurchases
This can become particularly important for U.S. investors during periods of elevated Treasury yields.
If the risk-free rate rises while a leveraged company's borrowing costs also increase, investors may demand a higher expected return from the stock.
That can pressure valuation multiples even before earnings decline.
By contrast, companies with strong balance sheets may have more flexibility to continue investing during downturns.
How Net Debt Affects Corporate Bonds
Bond investors focus heavily on a company's ability to meet its financial obligations.
As leverage increases and cash generation weakens, lenders may demand higher yields to compensate for additional credit risk.
The company's credit rating could also come under pressure.
This can create a negative cycle
Higher Leverage → Higher Credit Risk → Higher Borrowing Costs → Lower Cash Flow → Greater Financial Pressure
The reverse can also occur.
A company that generates substantial free cash flow and reduces leverage may improve its credit profile and potentially lower future financing costs.
For this reason, equity investors can learn a great deal by thinking like bond investors.
Before asking how much upside a stock has, ask
Can this company comfortably service its obligations if conditions become worse?
Net Debt, the Dollar, Gold, and Bitcoin
Net debt does not directly determine the price of the U.S. dollar, gold, or Bitcoin.
The relationship is indirect and runs through the broader liquidity and credit cycle.
When interest rates rise and credit conditions tighten, leveraged companies and investors may attempt to increase liquidity.
That can result in asset sales across multiple markets.
During severe liquidity events, even traditional safe-haven or alternative assets can experience temporary selling pressure because investors need cash.
When financial conditions eventually ease, capital can move back toward equities and alternative assets.
Therefore, net debt should not be treated as a tool for predicting gold or Bitcoin prices.
Instead, it helps investors understand a broader question
Where is financial vulnerability building when liquidity becomes scarce?
What Investors Should Check When Analyzing Net Debt
1. Why Is Net Debt Increasing?
Increasing net debt is not automatically negative.
A company might borrow to build a new semiconductor fab, expand cloud infrastructure, acquire another business, or invest in a project expected to generate attractive long-term returns.
But if debt is increasing because the core business cannot fund normal operations, the interpretation is very different.
Always investigate the reason behind the change.
2. Is Net Debt to EBITDA Rising or Falling?
Direction matters.
A company moving from 4x leverage toward 3x and then 2x may be strengthening its balance sheet.
A company moving from 1x to 2x to 3x deserves additional scrutiny.
3. Is the Company Generating Free Cash Flow?
Revenue growth alone cannot repay debt.
Sustainable cash generation matters.
Look at whether operating cash flow and free cash flow are sufficient to fund operations, investment, and debt service.
4. When Does the Debt Mature?
Two companies with identical net debt can have very different risk profiles.
One may have maturities spread over ten years.
Another may need to refinance billions of dollars within the next 18 months.
During periods of elevated rates, that difference can be critical.
5. Is the Debt Fixed or Floating Rate?
Floating-rate debt can expose a company more quickly to higher benchmark interest rates.
Long-term fixed-rate financing can delay that pressure.
6. Is the Cash Really Available?
Not every dollar classified as cash or investments is necessarily available for immediate debt repayment.
Some liquidity may be restricted, held by subsidiaries, or required for normal business operations.
Detailed analysis should therefore focus on usable liquidity, not simply the largest cash number on the balance sheet.
7. How Does Leverage Compare With Competitors?
Capital structures vary enormously by industry.
A software company should not automatically be judged by the same leverage standards as a utility or telecommunications company.
Peer comparisons provide essential context.
Why Net Debt Should Never Be Used Alone
Net debt is useful, but it cannot tell investors whether a company is fundamentally attractive.
A net-cash business can still be losing market share, destroying capital, or operating in a structurally declining industry.
A company with significant net debt can still create substantial shareholder value if its debt is inexpensive, manageable, and invested into projects producing attractive returns.
The real analysis involves three questions
How much debt does the company have?
How much cash can the business generate?
How effectively does management allocate that cash?
A strong balance sheet does not necessarily mean having zero debt.
It means having a capital structure the underlying business can reasonably support across different economic environments.
What Do Wealthy Investors Look for in This Trend?
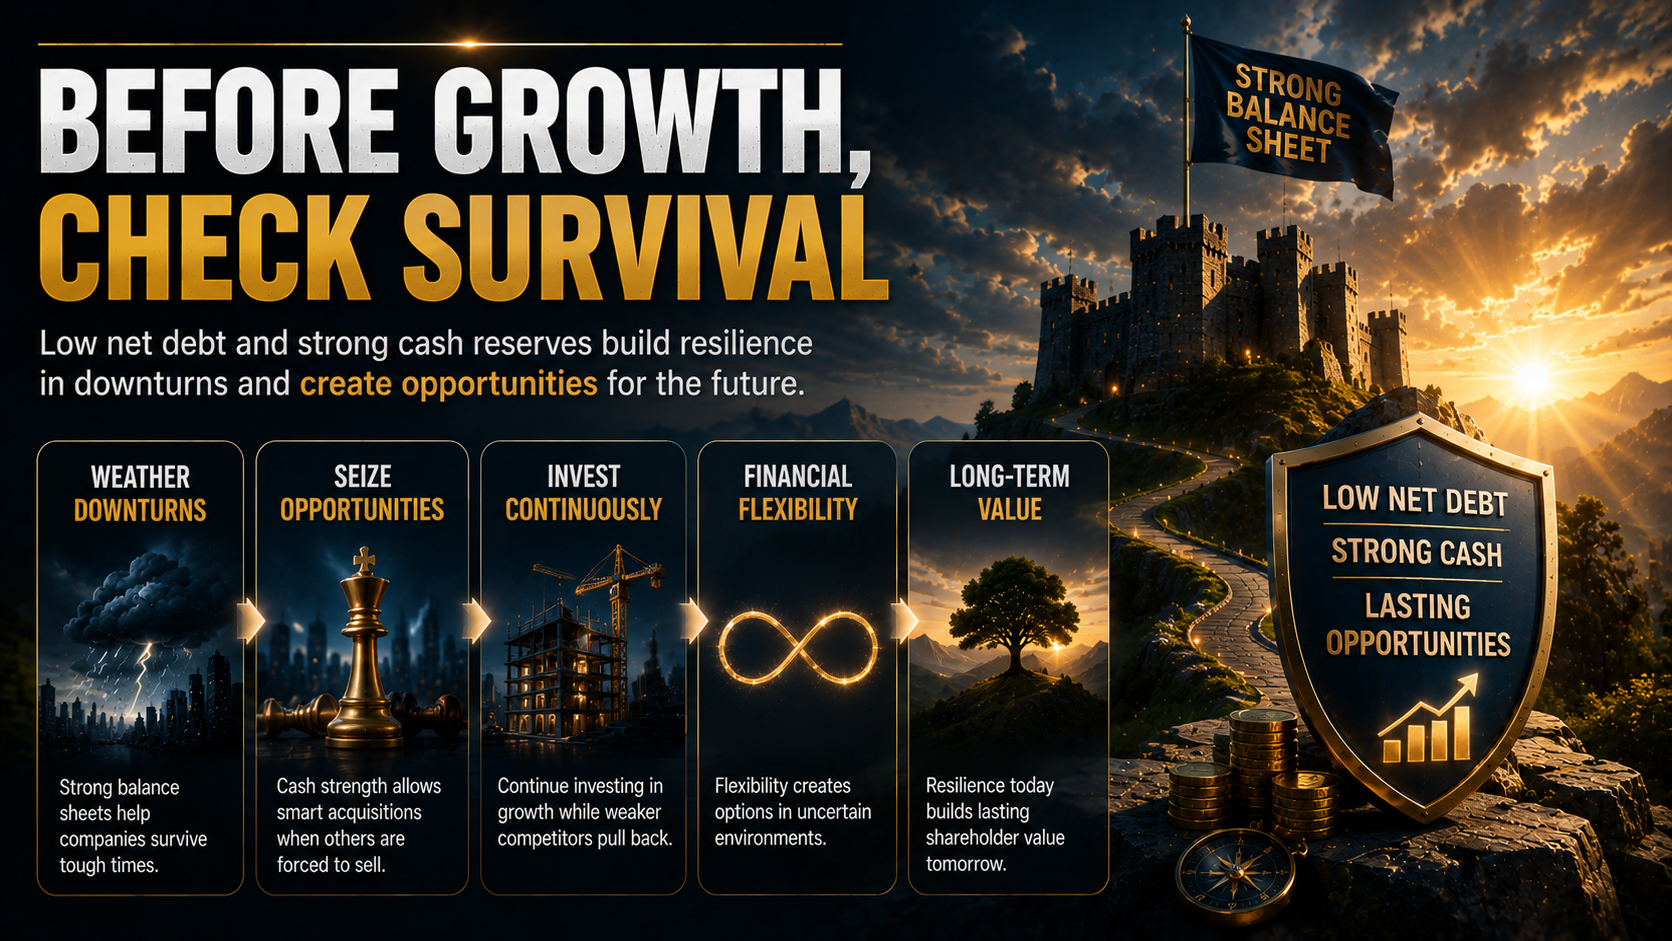
Long-term capital tends to look beyond headline earnings.
The more important question is how cash moves through the business.
Follow the Money
If most operating cash flow must continually be used to service debt, management has fewer strategic options.
If debt obligations are manageable, capital can instead flow toward R&D, capital expenditures, acquisitions, dividends, or share repurchases.
Financial flexibility has value because it creates choices.
Follow the Cash Flow
Suppose revenue and earnings keep rising while net debt climbs even faster.
Investors should ask
Is this company truly creating cash, or is debt financing creating the appearance of growth?
Accounting profits can fluctuate because of assumptions and non-cash items.
Debt ultimately requires real cash.
Look for Financial Survivability
Recessions, credit crises, pandemics, commodity shocks, and unexpected interest-rate cycles are difficult to predict consistently.
That makes another question more useful
Could this company survive if external financing became expensive or temporarily unavailable?
This is where balance-sheet strength becomes strategic rather than merely defensive.
Think About the Next Cycle
A downturn can be a crisis for financially weak companies and an opportunity for financially strong ones.
Cash-rich companies may be able to acquire assets at distressed prices, continue investing while competitors cut spending, hire talent, expand market share, or repurchase shares when valuations are depressed.
The strongest balance sheet does not always produce the highest return.
But financial flexibility can determine which companies are still capable of playing offense when everyone else is forced to defend.
For investors, that leads to several useful questions
- Can the company service its debt during a recession?
- Does the business consistently generate operating and free cash flow?
- Are major debt maturities approaching?
- Could the company withstand higher interest rates for longer than expected?
- Is cash being invested productively?
- Could the company continue investing if competitors were forced to cut spending?
- Is leverage creating future cash flow, or merely financing current weakness?
Investing is not only about predicting which company will grow the fastest.
It is also about identifying which businesses can survive when the forecast is wrong.
Final Thoughts
Net Debt is one of the most useful metrics for understanding a company's true financial position.
It adjusts headline debt for available cash and gives investors a clearer view of effective leverage.
But the number should never be analyzed in isolation.
Investors should examine why net debt is changing, how much free cash flow the company generates, its Net Debt to EBITDA ratio, interest costs, debt maturity schedule, and the stability of the underlying business.
Ultimately, the most useful question is not
“How much debt does this company have?”
It is
“Can this business comfortably carry its debt while continuing to generate enough cash to invest in its future?”
Growth attracts attention during bull markets.
Financial resilience often determines who survives the difficult periods and enters the next cycle with the ability to invest.
That is the deeper value of Net Debt analysis.
MasterMind.
'[Global] Success Blueprints' 카테고리의 다른 글